


2024 represented a significant low point for domestic real estate investments, and 2025 brought lower-than-expected GDP growth, but expectations for the upcoming year seem optimistic, both for Hungary’s macroeconomic forecast and the country’s property investment market.
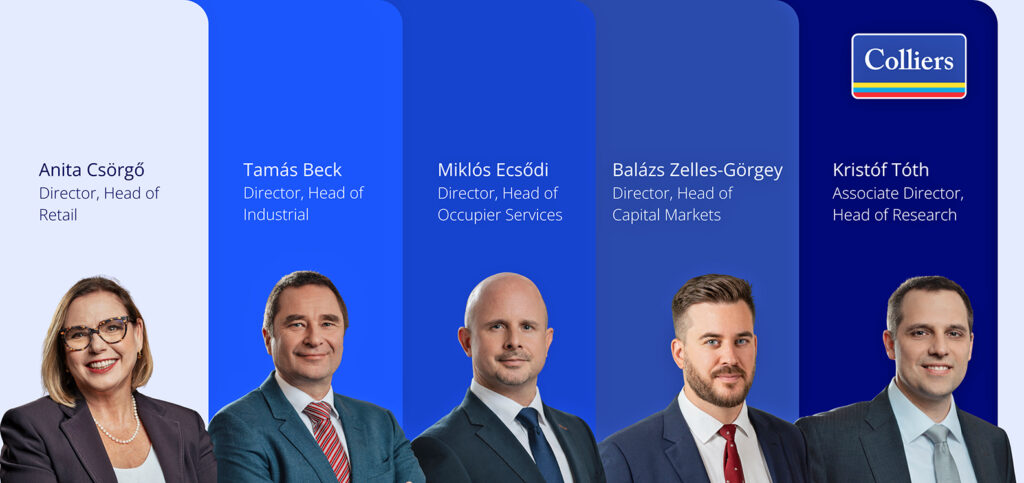
“Even though 2025 brought lower-than-expected GDP growth due to factors such as slow industrial production and external consumption, we can expect it to accelerate by 0.4-0.5%, and economic growth is projected at 2-3% for 2026”, explained Kristóf Tóth, associate director, head of research at Colliers Hungary.
“There was a pretty significant wage increase in 2025, something we’re also expecting this year, with an 9-9.5% increase in nominal wage, paired with a 4-5% real wage increase. This was a response to both inflationary pressures and a tight labor market. The unemployment rate was 4.4% in December, and we’re not expecting any significant change in this area,” Tóth added. It wasn’t the only area of good news.
“2025 was a turning point in Hungary’s real estate investment market, with a total investment volume of EUR 881 million, exceeding the record-low 2024 figure by 117.5%,” shared Balázs Zelles-Görgey, director, head of capital markets at Colliers Hungary.
The most sought-after sectors for investment were office (with a 50.8% share), hotels (18.3%) and industrial (17.4%). The largest transactions in terms of square meters in 2025 included the second and third warehouse buildings at HelloParks Páty (23 km west of central Budapest by road), as well as the IP West office building and the Science Park business center, both in Budapest.
“Hungarian investors are still dominating the market, as 64% of the current volume is connected to domestic buyers. International investors remained cautious, driven by a combination of global, regional, and local factors,” said Zelles-Görgey. “Western European core investors are still primarily present on the sell side across the entire CEE region,” he added,
The office building submarket had a successful 2025, with a year-on-year decrease in vacancy and speculative vacancy, an increase in net demand, and overall positive net absorption of nearly 100,000 sqm.
Speculative office completions totaled over 80,000 sqm across 2024-2025, of which 32.2% remains vacant. The largest handover was the Liberty North Wing at 19,779 sqm. As of Q4 2025, the overall market speculative vacancy rate had steadied at 15.9%, with Central- and North Buda recording the lowest vacancies.
Total office transaction volume in Budapest increased by 0.7% last year, “driven largely by governmental owner-occupier transactions at Dürer Park,” according to Miklós Ecsődi, director, head of occupier services at Colliers.
He also highlighted that the total speculative office pipeline through Q4 2028 is “limited, amounting to just 138,900 sqm.” Of this, less than 50,000 sqm is expected to be delivered before the end of 2026. The pipeline is mostly condensed in the Váci Corridor, accounting for 89% of the total construction volume; the most significant projects, including Centerpoint III, H2O Offices phase II, and the Láng Negyed V1 Building, are all located within this submarket.
The industrial sector also experienced a productive year in terms of leasing activity and overall net absorption. The total handover of industrial completions in 2025 was more than 476,000 sqm, of which 37% is vacant. Some 69% of the completions are located in Budapest, the remaining 31% in the countryside.
The total net take-up in Greater Budapest was 447,820 sqm, a nearly 80,000 sqm increase from the previous year. Pre-leases accounted for the largest share, followed by new leases and expansions, finishing “strong” in the last quarter of the year, with a 45% share of net take-up volume.
Seventeen industrial handovers in 2025 surpassed 10,000 sqm. According to Tamás Beck, director, head of industrial agency at Colliers Hungary, transactions of this volume have been increasing since the COVID-19 pandemic.
The total of industrial pipeline under development is 551,458 sqm, with 43% of the space pre-leased. Budapest accounts for 300,681 sqm, with a 53% pre-lease rate; the remaining 250,777 sqm is located in the countryside, with a 60% pre-lease rate.
Beck also commented that larger property developments are being made across the farther eastern regions of Hungary, highlighting cities such as Debrecen (230 km east of the capital) and its surroundings, and Miskolc (185 km northeast), as well as in Nyíregyháza (237 km east) and Kecskemét (93 km southeast of Budapest).
Regarding the domestic retail market, Anita Csörgő, director, head of retail agency at Colliers Hungary, noted that there is less emphasis on building new shopping centers. Investments are instead being concentrated on renovating existing assets. The only upcoming major development is the demolition and rebuilding of a “larger and more upscale” Duna Mall in Budapest, scheduled for completion in 2029.
The development of multiple retail parks has also halted due to the September 2025 revision of the so-called “Plaza Stop” regulations, and many projects have been put on hold ahead of April’s national elections. Although smaller centers with supermarkets and a few additional stores are opening outside of the capital city, these “are not counted as shopping centers as per the ICSC standards,” Csörgő explained.
She predicted that the continuation of the Home Start program will “further push out-of-city family housing developments in areas with limited retail offer, making those areas ideal locations for future retail parks.”
According to Csörgő, there was a strong correlation observed between the country’s increase in foreign tourism and a rise in retail spending. Tourism has led to an upswing in high street retail on Váci utca, Fashion Street, and Andrássy út. With more than 7% y.o.y. growth in foreign guest nights, Hungarian tourism saw a total of around 47 million guest nights, according to the Ministry for National Economy. The effects were felt “especially around the city center and high streets, such as Váci út and surrounding areas.”
Predictions for the upcoming year are confident in the development of peripheral industries and foreign investment.
“International institutional investor activity is increasing in certain CEE countries, especially Poland and Czechia, which may result in capital flowing into Hungary in 2026, provided there is EU determination and improvement in the economic environment,” Zelles-Görgey said.
“Conversion opportunities, repurposing, and residential sectors are expected to become increasingly attractive. Secondary assets, mainly offices, can still generate attractive returns if [they are] repositioned to meet flexible layouts and ESG requirements,” he concluded.
This article was first published in the Budapest Business Journal print issue of February 13, 2026.


